Selasa, 13 Juni 2006

BEHAVIORAL FINANCE VS. EFFICIENT MARKET THEORY

There is an ungoing dispute between some scholars from financial universities and others over the effectiviness of technical analyses for predicting market movements.


Since the random walk model contends that price fluctuations occur randomly, technical systems which rely upon the existence of price trends cannot be profitable in the long run. The thought of a random walk being a condition and also an indication for the existence of an efficient market. Supportes of this theory deny the possibilty of predictability of pices on the stock market.


Others don't agree with this. There are studies that technical analyses do work, while even some question the efficient market theory itself eg. behavioral economist's as Tversky, Kahneman and Barberis. Some articles can be found below.


SUBSCRIBE THIS FEED

Kamis, 08 Juni 2006

SYSTEM DEVELOPMENT (AGAIN)

There are many aspects on trading which must be adressed before trading a system. Some of them can be found in the sidebar under Interesting Posts. The following will be treated on a next occasion.

  • consistency

  • robustness

  • traders psychology and behaviour


As allways I am looking for new tradesytems besides retesting the current in use. You never know what the results will be of these exercises. One of the most compelling aspects of trading is the valuation of the drawdowns of a system. A drawdown defined as the maximum top-to-valley drop in the equity curve.


Drawdowns can be seen as extreme events in a ditribution of possibble events but due to their extreme values they are almost allways underestimated in statistics, especially in normal distributions.


A relatively new research field of statistics considers extreme values. This so called Extreme Value Theory not only studies the markets but has also applications to other fields as floodcontrol, sea waves and material exhaution models and so on.


The mathematics is as usual interesting but really very complicated. I will try to give a survey of my findings another time. Some articles:

The last couples of day I performed some trades, see my FDAX Trades and my DOW JONES Trades.


SUBSCRIBE THIS FEED

Kamis, 01 Juni 2006

LUCK AND RANDOMNESS

There is no doubt that luck or more general speaking randomness plays an important and unpredictable role in trading. Nobody can escape from this, be it in business, science, love or trading.


A computer simulation of a portfolio starting with equal amounts of money and trading the same system (win ratio of .6 and profit/loss factor of 1) reveals the following result. It is by any means a profitable system but while some portfolio's made a nearly 140% return, others suffer from bad drawdowns to only a 60 % return. This cannot be attributed to skillness or whatever, but is just a matter of randomness or luck which alters someones result. See graph below.
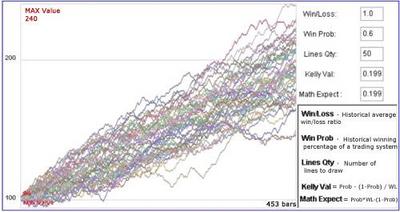


KEEP THIS IN MIND when trading, I find this a very disturbing but also a very reassuring thought at the same time, not everything is in our hands.


I traded yesterday very carefully on the FDAX before the FED's announcements. I never trade on news and I try to avoid these to interfer with my decisions but I know all to well that some news can disturb the markets on the short term very heavily and FED news is one of those newsfacts. My entries are given in the next chart arrowed at the upper side of the graph.
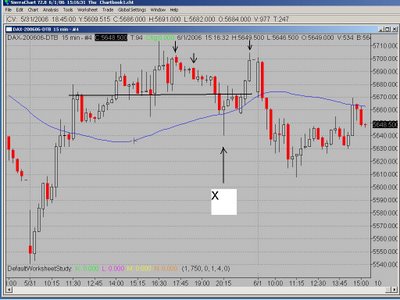


I traded the intraday 5670 level (lined). At arrow X, I hesitated to go short. I connected these moves with the FED and I decided not to enter. I was clearly lucky, no skill, just lucky. Later on the evening I entered long.


The DOW JONES for a couple of days now finding resistance at the 200 SMA. Also bouncing off the support at 1245. See S&P 500 today


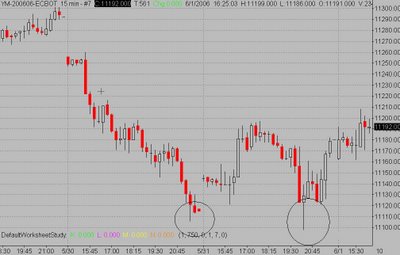
Looking at the markets today I am wondering if the DOW futue will show us up with a Adam and Eve doubble bottom, like the FDAX last week, see an intrady chart (eg. at yahoo finance), or below:


Related Posts Plugin for WordPress, Blogger...